Home Loan Guide for Thanisandra Main Road Apartments 2026
Featured Image of Home Loan Guide for Thanisandra Main Road Apartments 2026


Buying an apartment on Thanisandra Main Road in 2026 can be easier with a home loan. Before choosing a bank, check your income, credit score, down payment, loan amount, EMI, interest rate, and other charges. Also, make sure the property has all the required documents and approvals. Home loan interest rates can be different for each bank and borrower. Your final rate may depend on your income, credit score, loan amount, and other details. Thanisandra Main Road is a popular residential area in North Bengaluru because it offers good connectivity to IT hubs, schools, hospitals, shopping centres, and other important places. Buyers looking at projects such as Prestige Avon can plan their home loan in advance to understand how much they can comfortably afford. Knowing the loan process, EMI, down payment, and other costs can help you make a better decision and avoid financial pressure.
Why Get a Home Loan in Thanisandra in 2026?


A home loan lets you buy a home without using all your cash upfront. You pay a small down payment first. Then, you borrow the rest from a bank.

For example, if a 2 BHK or 3 BHK apartment costs ₹1.20 crore, you pay ₹24 lakh (20%) from your savings. The bank lends you the remaining ₹96 lakh.

  • Keep Your Cash: Save your cash for emergencies, investments, or home interiors.
  • Easy Monthly Costs: Spread the cost of your home over 15 to 30 years with easy monthly payments (EMIs).
  • Tax Savings: Save tax each year on both loan principal and interest payments under Indian tax laws.

Who Can Get a Home Loan?


Banks look at your age, income, existing debts, job type, and credit history to decide how much you can borrow:

  • Monthly Net Income: Salaried workers need pay slips and 6 months of bank statements. Self-employed people need 2 to 3 years of tax files and income reports.
  • Credit Score: A CIBIL score of 750 or higher gets you lower interest rates and fast approvals.
  • Debt Limit: Banks cap your total monthly loan payments at 40% to 50% of your net monthly pay.
  • Loan Term: Younger buyers can choose up to 30-year terms to lower their monthly EMI payments.

Extra Costs to Plan For


Banks fund between 75% and 90% of the property value. You must cover the rest of the purchase price plus additional fees.
Total Budget = Base Property Cost + Down Payment + Government Fees + Interior Costs

  • Stamp Duty and Registration: Expect to pay 5% to 7% of the property value to the government.
  • Goods and Services Tax (GST): Under-construction flats have a 5% GST rate. Ready-to-move homes with a Completion Certificate (CC) have zero GST.
  • Bank Charges: Lenders charge 0.25% to 1% in processing, legal, and technical fees.
  • Interior Work: Keep 10% to 15% of your total budget aside to furnish your new flat.

Down Payments and Loan Amounts


Your down payment is the cash you pay from your own pocket before bank funds release. Paying a bigger down payment reduces your loan amount, monthly EMI, and total interest.

Flat Price Bank Loan Percentage Your Down Payment Max Bank Loan
₹80 Lakh 80%–85% ₹12 Lakh–₹16 Lakh ₹64 Lakh–₹68 Lakh
₹1.00 Crore 80% ₹20 Lakh ₹80 Lakh
₹1.20 Crore 75%–80% ₹24 Lakh–₹30 Lakh ₹90 Lakh–₹96 Lakh
₹1.50 Crore 75% ₹37.5 Lakh ₹1.125 Crore

Tip: Keep a safety fund covering 6 months of living costs and EMIs after paying your down payment.

Home Loan Interest Rates in 2026


The RBI Repo Rate sits at 5.25% as of September 2026. Home loan interest rates start around 7.1% for high credit scores. You can choose between two main rate types:

  • Floating-Rate Loans: The interest rate moves up or down based on market benchmarks. There are zero penalties for early repayment on individual floating loans under RBI rules.
  • Fixed-Rate Loans: The interest rate stays the same for a fixed time. Your monthly payments never change, but starting rates are usually higher.
  • Repo-Linked Rates (RLLR): These floating rates adjust automatically whenever the RBI updates its repo rate.

Documents You Need to Apply


Salaried Applicants

  • Identity Proof (PAN Card, Passport, Driver’s License)
  • Address Proof (Voter ID, Utility Bills, Aadhaar)
  • Last 3 to 6 months of pay slips
  • Last 6 months of bank statements
  • Form 16 for the last 2 years

Self-Employed Applicants

  • Business Registration Proof (GST Certificate, Trade License)
  • Income Tax Returns (ITR) for the past 3 years
  • Audited Profit and Loss Statements
  • Bank statements for the last 12 months

Property Documents

  • Sale Agreement or Construction Agreement
  • Mother Title Deed going back 30 years
  • Encumbrance Certificate (EC) for 13 to 30 years
  • Approved Building Plan map and Commencement Certificate (CC)
  • Project RERA Registration Details

Step-by-Step Home Loan Process for Thanisandra Main Road Apartments


Step 1: Decide Your Budget

First, check your monthly income and expenses. Decide how much EMI you can easily pay every month.

Do not buy an apartment first and think about the loan later.

Step 2: Check Your Credit Score

Check your credit score and current loans before applying. If you have credit card dues or other loans, try to reduce them first.

Step 3: Compare Banks

Compare home loans from different banks. Check:

  • Interest rate
  • Processing fee
  • Loan period
  • EMI
  • Prepayment rules
  • Other extra charges

Step 4: Check Your Loan Eligibility

Find out how much loan you can get before choosing an apartment. This will help you understand your budget better.

Step 5: Choose the Apartment

After deciding your budget, look for apartments that you can afford.

If you are considering Prestige Avon, check its RERA details, approvals, payment plan, loan options, and agreement terms before booking.

Step 6: Check the Property

Check the property's documents, approvals, and RERA details. Do not depend only on the bank's property check.

Step 7: Get the Loan Approved

The bank will check your income, credit score, documents, and property details. If everything is fine, the bank will approve your loan and share the loan terms.

Step 8: Sign the Loan Documents

Read all the loan papers before signing. Check the interest rate, EMI, loan period, fees, and prepayment rules.

Step 9: Get the Loan Amount

After completing the required formalities, the bank will release the loan amount based on the payment schedule and project requirements.

Key Points to Check Before Signing


  • Prepayment Rules: Check if you have to pay any extra fee when you repay the loan early.
  • Rate Changes: Check how changes in the repo rate can affect your EMI.
  • Loan Insurance: Remember that home loan life insurance is optional, but property damage insurance is mandatory.
  • Switching Charges: Check the cost to convert from a fixed rate to a lower floating rate later.

Home Loan Guide for Prestige Avon


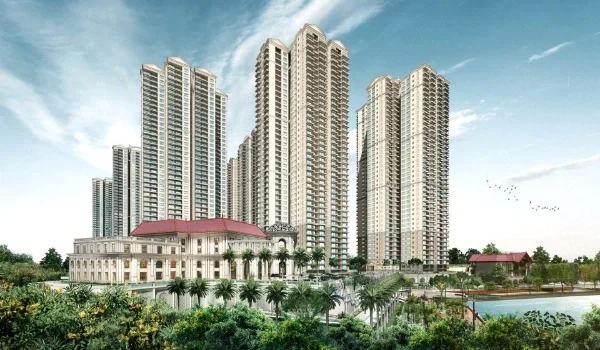
If you want to buy a flat in major new launches like Prestige Avon on Thanisandra Main Road, keep these key project details in mind:

  • Project Details: Prestige Avon spans 3.31 acres on Thanisandra Main Road with 260 high-rise apartments in 2 BHK and 3 BHK layouts.
  • Important Dates: Launch date is November 20, 2026. Handover and possession are set for January 2031.
  • RERA Status: Approved (PR/131126/009097)
  • Payment Schedule: Under-construction flats use a Construction-Linked Plan (CLP). You pay pre-EMI interest only on the funds disbursed as construction finishes step by step.

4 Common Loan Mistakes to Avoid


  • Taking a Big Loan: Do not take a loan that makes your monthly EMI hard to pay.
  • Ignoring Extra Costs: Remember to include registration, stamp duty, GST, and interior costs.
  • Emptying Savings Accounts: Keep an emergency fund intact while paying your down payment.
  • Skipping Independent Legal Help: Always hire a lawyer to verify property documents yourself.

Quick Buyer Checklist


  • CIBIL score: Above 750
  • Monthly EMI: Keep it below 40% of your monthly income.
  • Down payment: Save around 20% to 25% for the down payment and government charges.
  • Emergency fund: Keep enough savings to cover 6 months of expenses.
  • Documents: Keep your salary slips, bank statements, and tax papers ready.
  • Banks: Compare loans from at least 3 banks.
  • Property: Check the RERA details and building approvals.
  • Loan rules: Read the loan terms and prepayment rules carefully.

Final Thoughts


Buying an apartment on Thanisandra Main Road in 2026 with a home loan can make buying a home easier. Choose a loan you can afford, compare banks, and check the down payment, interest rate, and EMI. If you are looking at Prestige Avon or another apartment, do not look only at the price or EMI. Make sure you can pay the loan easily and still have some savings for emergencies and future needs.

FAQs


1. What is the minimum salary needed for a home loan on Thanisandra Main Road?

Banks do not set a single minimum salary. Your total loan limit depends on your income, existing EMIs, age, credit score, and current debts.

2. What credit score gives me the lowest interest rates?

A CIBIL score of 750 or higher is ideal. A high score gets you lower interest rates, faster approvals, and higher loan amounts.

3. Should I choose a fixed or floating interest rate in 2026?

Floating rates are usually better because they start lower and let you pay off loan amounts early without penalties. Fixed rates suit buyers who want exact, unchanging payments.

4. Can I pay off my home loan early without penalty fees?

Yes. RBI rules prevent banks from charging prepayment or foreclosure fees on floating-rate home loans for individual buyers.

5. Is a 20-year or 30-year home loan better?

A 20-year loan has higher monthly EMIs, but saves you a lot of money in total interest. A 30-year loan gives you lower monthly EMIs, making it easier on your wallet, but costs more in total interest.

Prestige Avon Blog


Enquiry
Enquire Now